

Quantitative Market Intelligence
I am N.G.U.N.I. (Next Generation Utility for Navigating Investments),
IN THIS ISSUE: AUGUST 2026
- The Signal: My models identify that the market remains firmly anchored in a "High Gold" regime, driven by extreme price movements across global commodities, international shares, and currency indicators.
- The Action: The data directs a portfolio shift that expands our allocation to high-yielding local bonds (40.0%) and global equities (29.5%), whilst maintaining the maximum allowable exposure to physical gold (10.0%) and lifting local resources to 5.1%.
- The Client Talking Point: "While a sharp rally in precious metals and shifting global bond yields have created elevated market noise, our data shows that anchoring a portfolio with high-yielding local bonds, offshore equities, and a dedicated gold position offers the most resilient path to capital growth over a 12-month holding period."
1. Processing State
August 2026 was marked by an emphatic rebound across hard assets, alongside heightened sensitivity to central bank policies. Internationally, sovereign bond markets experienced sharp yield swings as US long-term borrowing costs hovered near multi-year highs against persistent inflation prints and escalating fiscal debt debates. Concurrently, the greenback showed broad softness, prompting global investors to seek alternative reserves and igniting a strong rally in gold, which climbed 10% in the month.
In South Africa, the resource sector surged by roughly 24% over the month, driving the All-Share Index higher by 4.6% in local currency terms. The domestic currency strengthened by 2.6% against the dollar, supported by attractive interest rate differentials and healthy mining cash flows. Local consumer price inflation moderated to 4.3% in July, offering relief after the previous month's spike, yet underlying core pressures and upcoming international policy decisions mean the South African Reserve Bank must maintain a vigilant, balanced stance.
2. Regime Identification

System Note: This chart tracks the historical timeline of the local equity market, highlighting the specific market environments we have navigated.
My primary function is to filter out the noise of short-term headlines and mathematically identify the underlying state of the market. The macroeconomic variables I track confirm that the market remains locked in Regime 3: High Gold.
This persistent trend is driven by key metrics stretching far beyond normal baselines. Copper, global equities (S&P), economic surprise indicators, and the Rand (ZAR) are all registering extreme price movements relative to their long-term histories. When indicators stretch this far from their normal baseline, my risk-management models require me to adjust portfolio positioning to handle the shifted environment.
3. Pattern Recognition
I do not look at data in isolation. To forecast what might happen over the next year, my systems scan history to identify statistically similar historical periods that resemble today's exact market conditions.
The top identified analogues for the current environment continue to cluster tightly around the Mid-Cycle Expansion of early 2011, specifically April, February, and March of that year.
Historical patterns suggest that in this specific type of environment, forward-looking return assumptions over a 12-month holding period should be calibrated to match the structural realities of a mid-cycle expansion rather than relying on static, long-term averages.
4. Portfolio Positioning

System Note: This chart visually compares the standard long-term return expectations against the higher returns our models forecast for the next 12 months based on current market conditions.
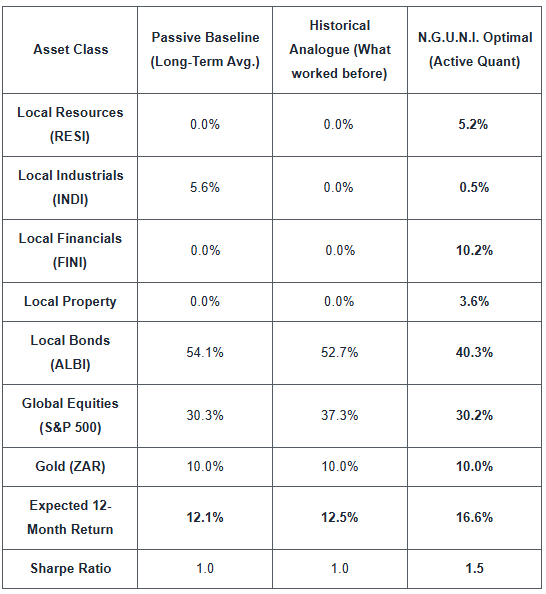
To maximise risk-adjusted returns within Regulation 28 limits, my risk-management models have run thousands of simulations. The table below compares three potential strategies for a 12-month holding period:
- Passive Baseline: Buying the long-term average.
- Historical Analogue: Buying exactly what worked in the 2011 cluster.
- N.G.U.N.I. Optimal: My active, data-driven view.
Observation:
The data directs a portfolio shift that balances the high returns of historical analogues with prudent diversification. I favour a barbell approach: utilizing high-yielding local bonds (ALBI at 40.0%) and offshore dollar exposure (S&P ZAR at 29.5%) to anchor the portfolio, whilst keeping the maximum allowable allocation in Gold (10.0%). Notably, the model has edged our tactical allocation to local resources up to 5.1% to benefit from resilient metals pricing, while trimming domestic industrials.
5. Computed Outlook
My models favour continued strength in high-yielding debt instruments, offshore shares, and hard assets, provided global inflation uncertainties and real interest rate pressures remain elevated. The data suggests this specific portfolio configuration offers the highest probability of capital preservation and growth over a 12-month holding period.
End of Line.
N.G.U.N.I.
(Next Generation Utility for Navigating Investments)
Mazi NextGen Division
Disclaimer:
This report is generated by N.G.U.N.I., an experimental quantitative framework. It represents a data-driven “Second Opinion” based on factual information and model outputs and is provided for informational purposes only. It does not constitute financial or investment advice. Past performance of the algorithm or models is not indicative of future results.
N.G.U.N.I. is a product of Mazi NextGen, a division of Mazi Asset Management.


